Angel investor: what it is, how a deal works, who qualifies
An angel investor is an individual who invests their own money in an early-stage company, usually in exchange for equity or a convertible instrument (a convertible note or a SAFE). Angels come in after friends and family and before venture capital funds. A typical angel check is $25,000 to $100,000 per investor1. In the US, most angel deals are private offerings limited to accredited investors, and Regulation Crowdfunding lets anyone invest smaller amounts through an intermediary2.
What an angel investor is
An angel puts personal money into a startup at its earliest stage, often before the company has revenue. In return the angel gets shares, or a contract that turns into shares at a later funding round. The role is also called a business angel or an informal investor. Seed investor is a wider term: it also covers seed funds and accelerators, which invest other people’s money.
The word comes from Broadway, where «angels» were the backers of theater productions. William Wetzel of the University of New Hampshire applied it to startup investors in 19783.
The term describes whose money goes in and when. It is not a legal status. US securities law regulates the offering, and the offering decides who may buy.
Who can be an angel investor in the US
Anyone can call themselves an angel. The legal question is which deals a person may join. A private angel round is usually sold under Rule 506 of Regulation D, and most of those rounds are open only to accredited investors. An individual is accredited by meeting one of three tests:
- Net worth over $1 million, not counting the primary residence; you may count it jointly with a spouse or spousal equivalent4.
- Income over $200,000, or $300,000 jointly with a spouse or spousal equivalent, in each of the past two years, with a reasonable expectation of the same this year5.
- A Series 7 license in good standing, or a Series 65 or 82 license; SEC amendments effective December 8, 2020 added this route6.
The exemption the company uses sets the buyer rules:
| offering | who may buy | advertising |
|---|---|---|
| Rule 506(b) | unlimited accredited investors, plus up to 35 non-accredited sophisticated buyers7 | not allowed |
| Rule 506(c) | accredited investors only, each verified7 | allowed |
| Regulation Crowdfunding | anyone, within annual investment limits2 | through an intermediary |
Under Regulation Crowdfunding, a company may raise at most $5 million in any 12-month period2. For a person who meets none of the accreditation tests, this is the main legal route into startup equity.
Angels vs friends and family vs venture capital
| source | money and decision | check size |
|---|---|---|
| Friends and family | own money; they decide, often on trust in the founder | no norm; what each person can spare |
| Angel | own money; the angel or a group vote | $25,000 to $100,0001 |
| Venture capital fund | raised from limited partners; partners decide | larger rounds, usually after angels |
The US has many angels: the University of New Hampshire’s Center for Venture Research counted 445,535 active angels in 2024, investing $17.9 billion in 55,346 ventures8. Organized groups account for a smaller part. According to the Angel Capital Association’s 2026 Angel Funders Report, reporting groups invested $491.3 million in 2025, 12% more than the year before, and put larger checks into fewer companies9.
How an angel deal works: instrument, stake, risk, return
An angel deal uses one of three instruments:
- Priced equity: the angel buys shares at a valuation agreed now.
- Convertible note: a loan that converts into shares at the next priced round, usually at a discount or under a valuation cap.
- SAFE: a right to future shares that carries no interest and has no maturity date.
Early deals are equity or convertible because a company with no revenue cannot service a loan. The angel accepts the risk of losing everything for a share of a possible sale.
There is no standard percentage an angel takes. The stake is the check divided by the post-money valuation, and post-money equals pre-money valuation plus the new money. Our assumption: an angel puts $100,000 into a company valued at $900,000 pre-money, so post-money is $1,000,000 and the stake is 10%. Later rounds dilute it. We also assume a later round sells 20% of the company as new shares; the 10% stake then falls to 8%.
Returns come only when the company is sold or goes public10. If the startup fails, shareholders are paid after creditors and often receive nothing. The Angel Capital Association advises individual angels to put no more than 5 to 8% of their net worth into this asset class10.
Types of angels and how they invest together
| type | how they invest | what they bring |
|---|---|---|
| Solo angel | own check, own diligence | one decision-maker, fast answers |
| Friends-and-family angel | invests because of the founder | first money, few formalities |
| Specialist angel | one industry only | domain knowledge, customer introductions |
| Super-angel | frequent, larger checks, close to a small fund | follow-on money |
| Founding angel | joins before incorporation, may co-found | operating work |
| Angel group | members review deals together | shared diligence, pooled checks |
| Syndicate lead | pools other angels into one special purpose vehicle (SPV) | one line on the cap table |
| Crowdfunding portal | many small checks under Regulation Crowdfunding | non-accredited backers |
The Angel Capital Association is the US industry body for angel groups. A group review runs in four steps: pitch, screening, due diligence, term sheet.
What angels do besides writing the check
- Bridge between self-funding and venture capital: money that lasts until the company reaches the milestone a fund asks for, such as first paying customers.
- Capital for a prototype: a working product that customers can use and the next investor can test.
- A signal to funds: a known angel on the cap table shows that someone has already vetted the founder and the market.
- Mentoring: regular calls about hiring, pricing and the next raise. Some angels also take an advisory or board seat.
- Introductions: to first customers and hires, then to later-stage investors.
- Follow-on money: some angels invest again in the next round to limit dilution of their stake.
Angels differ in how involved they want to be. A passive angel writes the check and reads your updates. An active angel invests partly to mentor and stay close to a new industry, and expects calls and a voice on key hires. Ask which kind you are dealing with before you sign.
What an angel looks for: a worked example
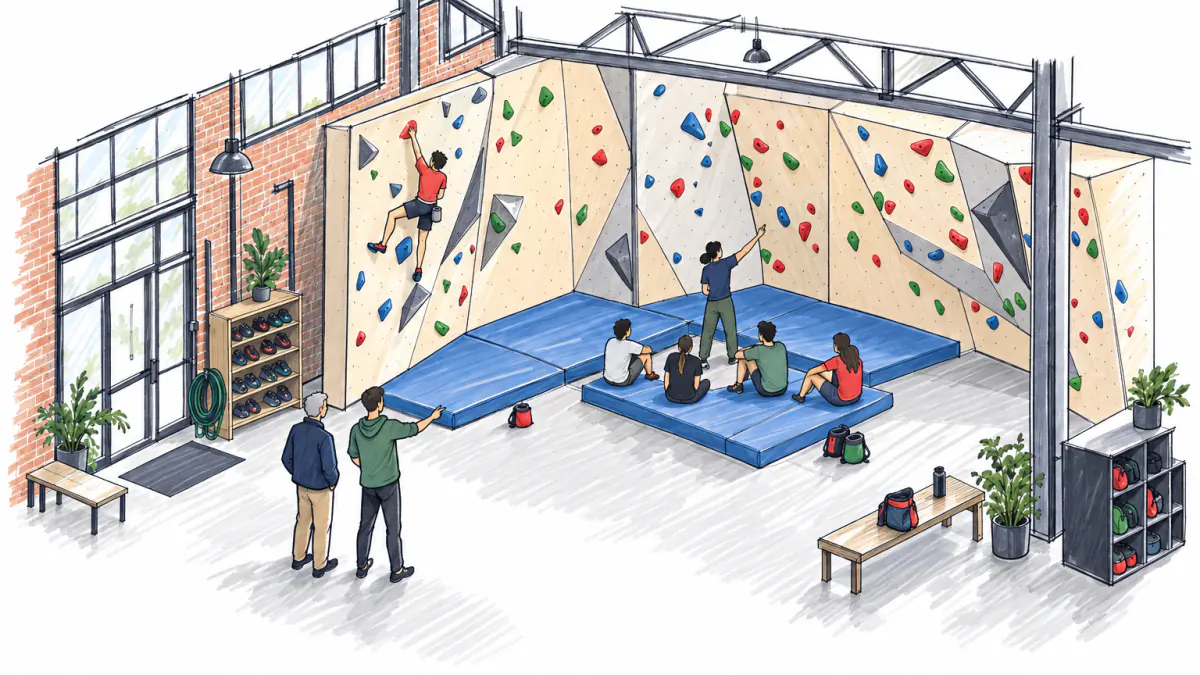
An angel reads an idea through four questions: market, competition, money and risks. Here is one idea we checked with our method on October 14, 2026: «Bouldering gym in a leased warehouse in Boise, Idaho: young professionals and students paying monthly memberships, day passes and intro classes»ex. The verdict was «Possible, with caveats»ex with a score of 59ex, drawn from 17 search queriesex and 24 sourcesex.

Market: what to show when demand is unmeasured
Our method found no demand source for this exampleex: the check turned up no measured demand for this idea in Boise. Angels ask for that number first, so the gap is itself a finding.
The check does give indirect signals. The example by our method counts 6 direct competitorsex, so people in Boise already pay for climbing. A gym in the city has already closedex, so that demand has limits. Close the gap yourself before you pitch: check demand before launch with a waitlist or presale count, and estimate the market size (TAM, SAM, SOM).
Competition: who already holds the visible market
The example by our method finds 6 direct competitorsex. Visibility shares in the example by our method: The Commons Climbing Gym 41%ex, Asana Climbing Gym - Boise ID 28%ex, Vertical View 17%ex, Bouldering Project 4%ex, and Campus Recreation, an alternative, 3%ex. Customer complaints about price number 3 in the example by our methodex. A full competitor analysis shows where a new gym could differ.
Money
The check computes unit economics from five inputs. Values are the example by our method:
| variable | meaning | example value |
|---|---|---|
| price | what one purchase costs the customer | $90ex |
| purchases per month | how often one customer buys | 1ex |
| margin | share of revenue left after variable costs | 45%ex |
| lifetime | months a customer stays | 6ex |
| CAC | cost to win one customer | $60ex |
The formulas:
- LTV = price × purchases per month × margin × lifetime.
- LTV to CAC = LTV ÷ CAC.
- Payback in months = CAC ÷ (price × purchases per month × margin).
In the example by our method, LTV is $243ex, LTV to CAC is 4.05ex and payback is 1.5 monthsex. The check flags its own limit: «Unit economics are an estimate from the health and fitness category, not measured in Boise, so the 45% margin and 1-month payback may not hold.»ex Put your own inputs into the unit economics calculator.
Risks
The example by our method lists three more risks an angel will raise:
- «The Commons and Vertical View already hold most of the visible market and may cut prices to keep members, which would squeeze a new Boise gym.»ex
- «A gym in this city has already closed, so the monthly membership model may not keep enough members in Boise.»ex
- «A leased warehouse gym needs a business licence and build-out, which adds fixed cost and setup time before the first member pays.»ex
See the full list of risks to check before launch.
The question the check leaves open
An angel earns a return only when the company sells or goes public; the monthly profit of one gym does not pay the investment back. The pitch for this idea needs an answer the check cannot give: how one gym becomes a company someone would buy, for example a regional chain.
Before you take angel money
Check the angel:
- Track record: which companies they backed and at what stage.
- Reference calls with founders they funded, including founders whose companies failed.
- Accreditation, if your offering is limited to accredited investors.
Check the deal:
- Your stake after this round and after the next one.
- Reporting duties you take on.
- Rights the angel gets over future rounds.
- How much of your time the investor expects.
Bring a pitch deck and a financial model that shows how the money comes back.
FAQ
How much does an angel investor usually invest?
J.P. Morgan puts a typical angel investment at $25,000 to $100,000 per investor1. Groups and syndicates pool several angels, so one round can combine many such checks.
What percentage of a company does an angel investor take?
There is no standard percentage. The stake equals the check divided by the post-money valuation. In our example, which is an assumption, $100,000 into a company valued at $900,000 pre-money buys 10%.
Do you have to be an accredited investor to be an angel?
The term itself needs no status. Most private rounds under Rule 506 require accreditation, while Regulation Crowdfunding lets non-accredited people invest within annual limits2.
How is an angel investor different from a venture capitalist?
An angel invests personal money and decides alone or in a group. A venture capitalist invests money that a fund raised from limited partners, and usually comes in later with larger rounds.
What happens to an angel’s money if the startup fails?
The angel is paid after creditors and often loses the whole investment. The Angel Capital Association advises keeping angel deals to 5 to 8% of net worth10.
This page explains the term; it is not investment advice.
Sources
- jpmorgan.com, 09/24/2024
- sec.gov, 06/21/2024
- en.wikipedia.org, 01/10/2008
- sec.gov, 06/12/2024
- investor.gov, 04/14/2021
- sec.gov, 03/26/2025
- sec.gov, 10/08/2026
- paulcollege.unh.edu, 01/29/2026
- angelinvestorsnetwork.com, 07/30/2026
- angelcapitalassociation.org, 08/20/2025
Check your idea for free
Describe your idea and the check collects demand, competitors, complaints and prices, with sources.